Product
- FootprintBid × ask on every level, delta, imbalances
- HeatmapResting liquidity through time, with memory
- CryptoBinance spot & perp, Bybit — same tools
- TradingDOM, OCO orders, account picker
- Chart demoThe crypto chart on a simulated market
- GEXDealer gamma, call and put walls
- VolatilityImplied volatility smile and skew
- Options flowPrints with the aggressor side when published
Learn
- Read a footprintThe starting point
- Order flowWhat the tape actually says
- Understand GEXGamma, walls, zero-gamma flip
- Options flowPremium, volume and classification
- Quant for beginnersFrom a hypothesis to an experiment
- All guidesSearch, paths, glossary, docs
Tested on the data you recorded,
not on a curve you fitted.
A strategy written in the editor runs bar by bar on your own recorded history. Coverage is measured before the run, costs are in the result, and walk-forward validation tells you whether the parameters survive data they never saw. It runs from Replay.
- Grid
- 400combinations at most
- Languages
- JS · Pythonno historical backtest for C++
- History
- Databentoimport a whole folder
Windows · macOS and Linux in beta · market data billed by your provider
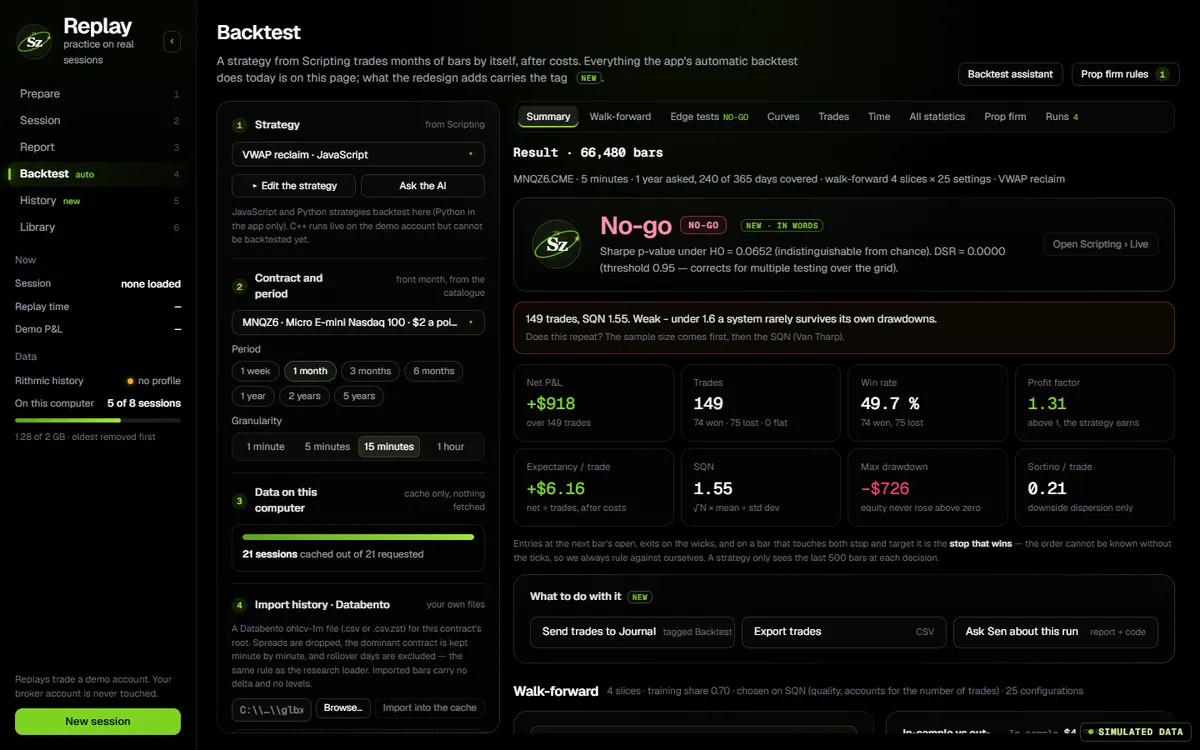
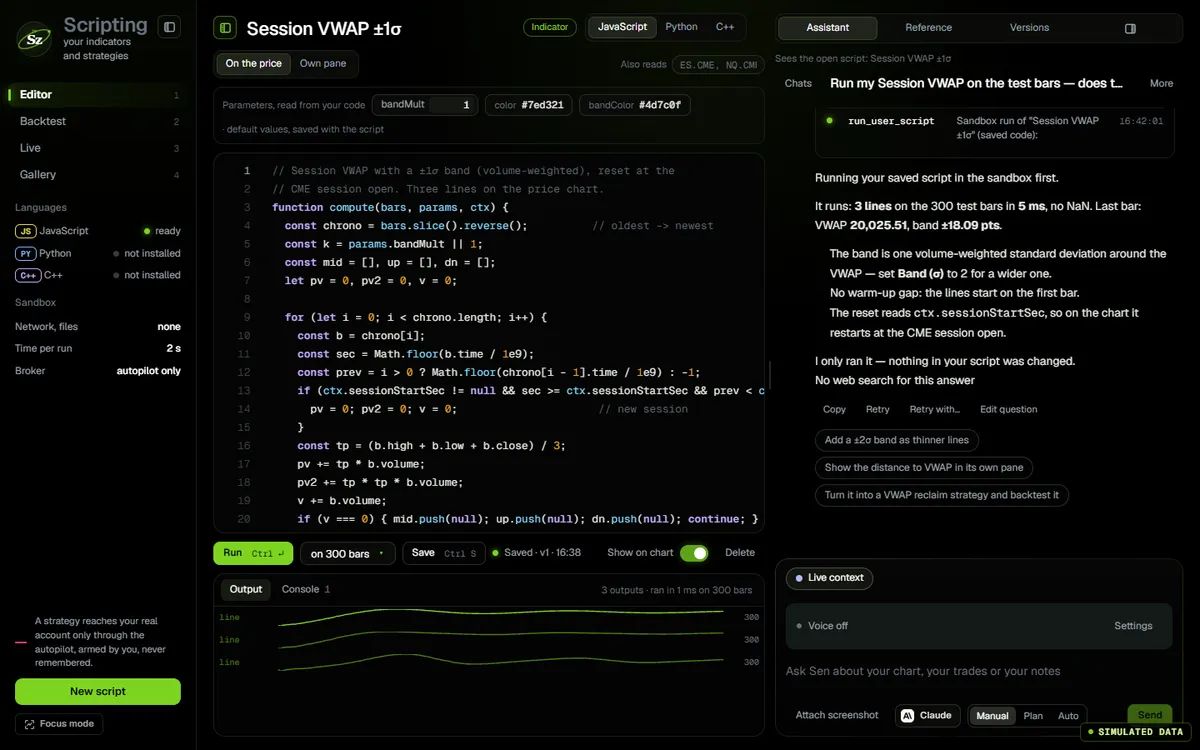
The app’s own code, compiled for the web and fed by a simulator. In the app, the same screen runs on your feed.
- 0.45Import a whole Databento folder for Replay and Backtest
- 0.80Scripts written by Sen are checked in the sandbox first
- 0.80The replay chart refuses live orders
Read a report
v0.88.1 of the app: Replay with the auto backtest.
The app’s auto backtest panel, v0.88.1, with a report on simulated MNQ bars: strategy, period, costs, walk-forward folds. Click the screen to use it; move the pointer away and the page scrolls again.
Your data
Coverage before conclusions.
- Recorded historyBars and ticks recorded from your broker connection, cached locally.
- Databento folder importChoose one folder of DBN or CSV files; trades keep their aggressor side, a day that is incomplete or a roll day is not written.
- Coverage, measuredWhat the cache holds for the window, and what a run would be missing.
The run
Bar by bar, costs included.
- Costs includedPoint value, commission per contract, slippage in ticks.
- Walk-forwardFolds, train ratio, objective: parameters optimised on one part, judged on the rest.
- RobustnessParameter grids (400 combinations at most), PSR / DSR / PBO and permutation tests.
- JavaScript and PythonHistorical backtests run both; C++ runs as indicators and in Replay.
The report
Numbers with the trades behind them.
- MetricsProfit factor, expectancy, SQN, Sharpe, drawdown, and the trades.
- Challenge simulationYour trades through configured evaluation rules (drawdown, daily loss, consistency, payouts), and Monte Carlo by permuting your days. A simulated pass does not predict a live one.
- An assistantReads the strategy and the numbers, proposes the next change as code.
How to read it
Costs, coverage and walk-forward, explained.
Works with
One app; every screen reads the same state.
- Replaynew pageWhere the backtest is launched, on the same recorded days.
- ScriptingThe strategy you test.
- Journal & notesA verdict, exported to the journal in one click.
Questions
The same list feeds the page and its structured data.
Is the backtest on this page real?
The panel is the one from the desktop app, byte for byte, and Run executes the strategy in your browser on a synthetic bar series. The numbers you see are computed by the same engine the app uses; only the data is simulated here.
What is walk-forward validation?
The period is cut into folds. On each fold the parameters are optimised on the first part (training) and the strategy is then evaluated, untouched, on the remainder (test). A strategy that only works on the training part shows it immediately.
Which data does the desktop app backtest on?
Bars and ticks recorded from your own broker connection, cached locally, or a whole folder of Databento files you import. Coverage is measured and shown before every run: a backtest on 12 percent of a session says so, and the report carries the coverage figure. The backtest is launched from Replay.
What costs are included?
Point value, commission per contract and slippage in ticks, all editable. Results are shown net of those costs, with profit factor, expectancy, SQN, Sharpe and the drawdown.
It is in the one plan
No add-on, no tier.
$9for 14 days
then $20 the first month and $29 a month after · every tool included · cancel any time